Dream Finders and Beazer: the two capital clocks of a homebuilder deal
A housing merger needs a bridge from acquisition funding to cash collected from completed homes.
On October 15, 2026, Beazer shareholders approved the Dream Finders acquisition. Dream Finders expects completion on October 20. That date remains an expectation. Company update.
The August 7 announcement set cash consideration at $33.50 per Beazer share and enterprise value at approximately $2.2 billion. Original transaction announcement.
Analysis: completion starts a second test
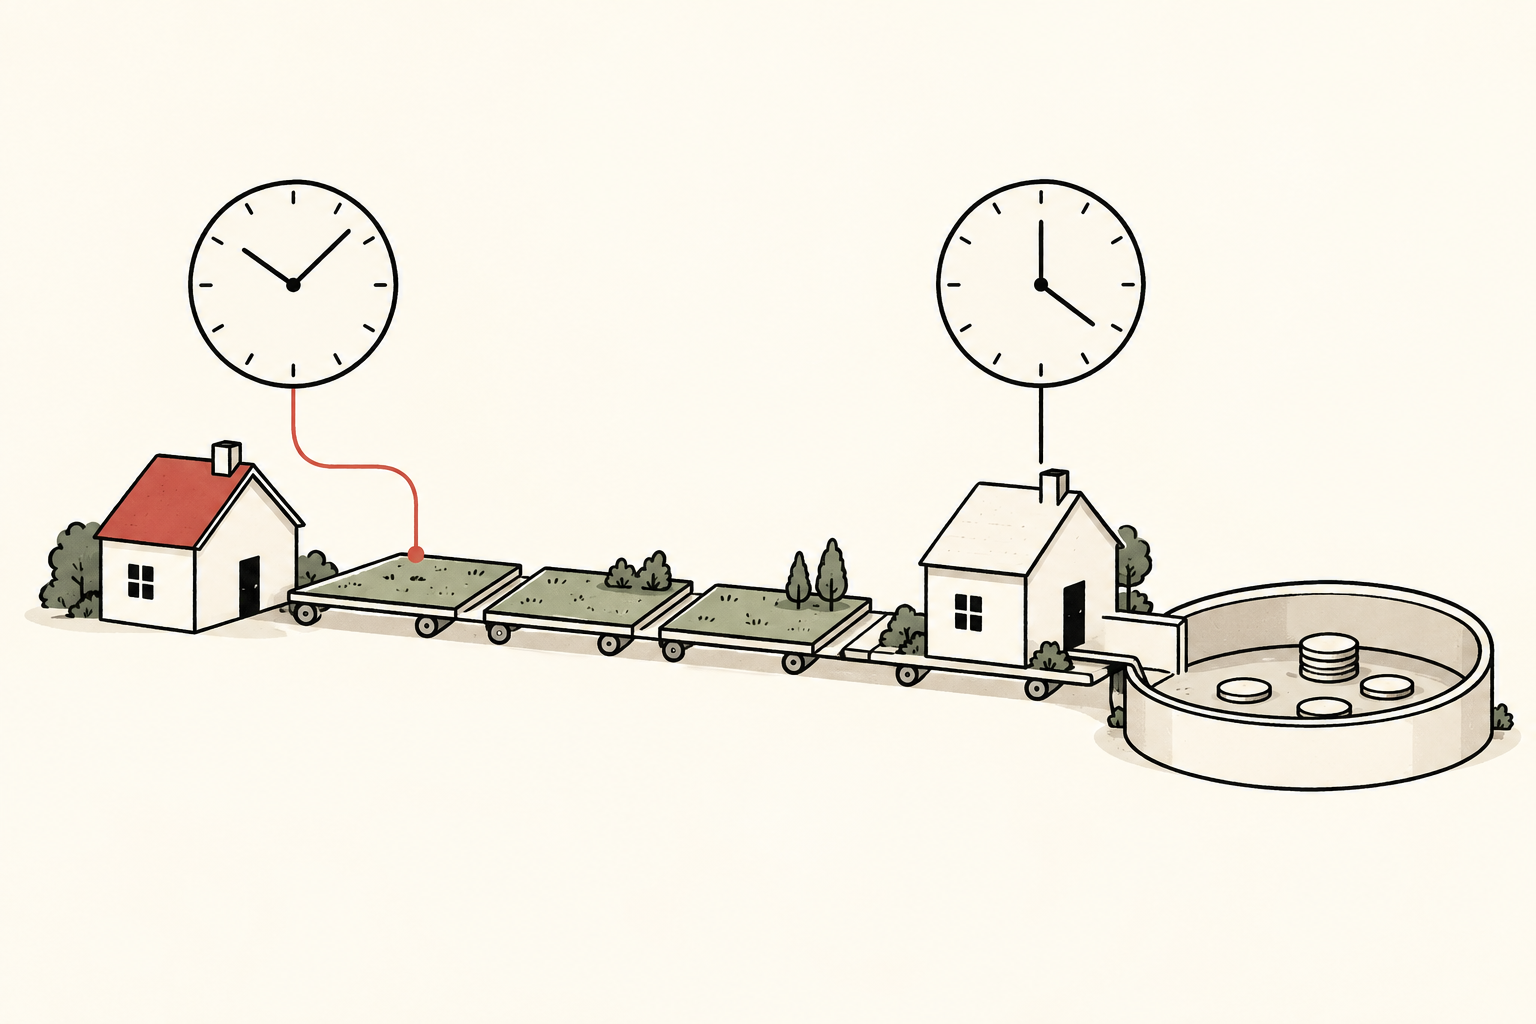
A homebuilder acquisition runs on two capital clocks. One measures how money reaches the seller at closing. The other measures how money invested in land, development and construction returns through completed-home sales. Moving the first clock forward does not automatically accelerate the second. This is the useful analytical distinction as the proposed combination approaches its expected completion date.
Consider a deliberately simplified example, not a forecast for either company. A buyer finances a business whose houses take longer to sell than anticipated. Purchase financing may remain fully available while operating cash is tied up for additional months. If the buyer instead sells homes faster by offering larger concessions, cash may return sooner but each sale may contribute less. Liquidity and margin can move in opposite directions. A completion announcement alone cannot resolve that trade-off.
What the funding documents add
An August 18 filing projected approximately $675 million of redeemable preferred stock after the merger; final financing terms remained subject to change. Capitalization disclosure.
A September 18 announcement said the 2032-note change-of-control amendment would become operative only after the consent fee was paid. Consent results.
For our analysis, contractual completion and operating cash generation need separate evidence.
For analytical purposes, preferred capital also deserves its own line rather than disappearing into a single debt number. The relevant questions are the eventual payment terms, redemption obligations and place in the capital structure. This article does not estimate those terms. Without the final documents, subtracting a headline funding figure from a headline purchase value would create a false impression of precision.
A more useful post-close scoreboard
An informative first reporting period would connect three bridges: opening capital, working capital and recurring operating performance. The opening-capital bridge would separate obligations inherited, financing raised and cash used. The working-capital bridge would explain how land purchases, development spending, construction and customer settlements changed cash. The operating bridge would distinguish underlying selling economics from transaction and integration effects.
The comparisons need consistent boundaries. A larger consolidated revenue total can reflect additional operations rather than stronger demand. A different inventory balance can reflect the acquired portfolio rather than a deliberate build-up. A seemingly better cash quarter can reflect timing rather than a permanently faster business. None of these possibilities is a claim about what the combined company will report; they are reasons to demand comparable starting points.
Similarly, purchasing efficiencies are most informative when the company explains where they appear: lower construction costs, reduced overhead, better delivery times or some combination. Counting the same benefit in several categories would overstate the improvement. A useful disclosure would reconcile the categories rather than simply repeat a combined savings target.
What remains unresolved
The immediate factual question is whether completion occurs as expected. The longer analytical question is whether the funding structure gives the operating business enough flexibility while its inventory turns into cash. A transaction can pass its closing milestone while the answer to that second question remains open. That is the distinction readers should preserve; it is not a valuation conclusion or an investment recommendation.
Information only. No investment, legal, tax, or financial advice.