ASGI: The Cost of Partial Take-Up
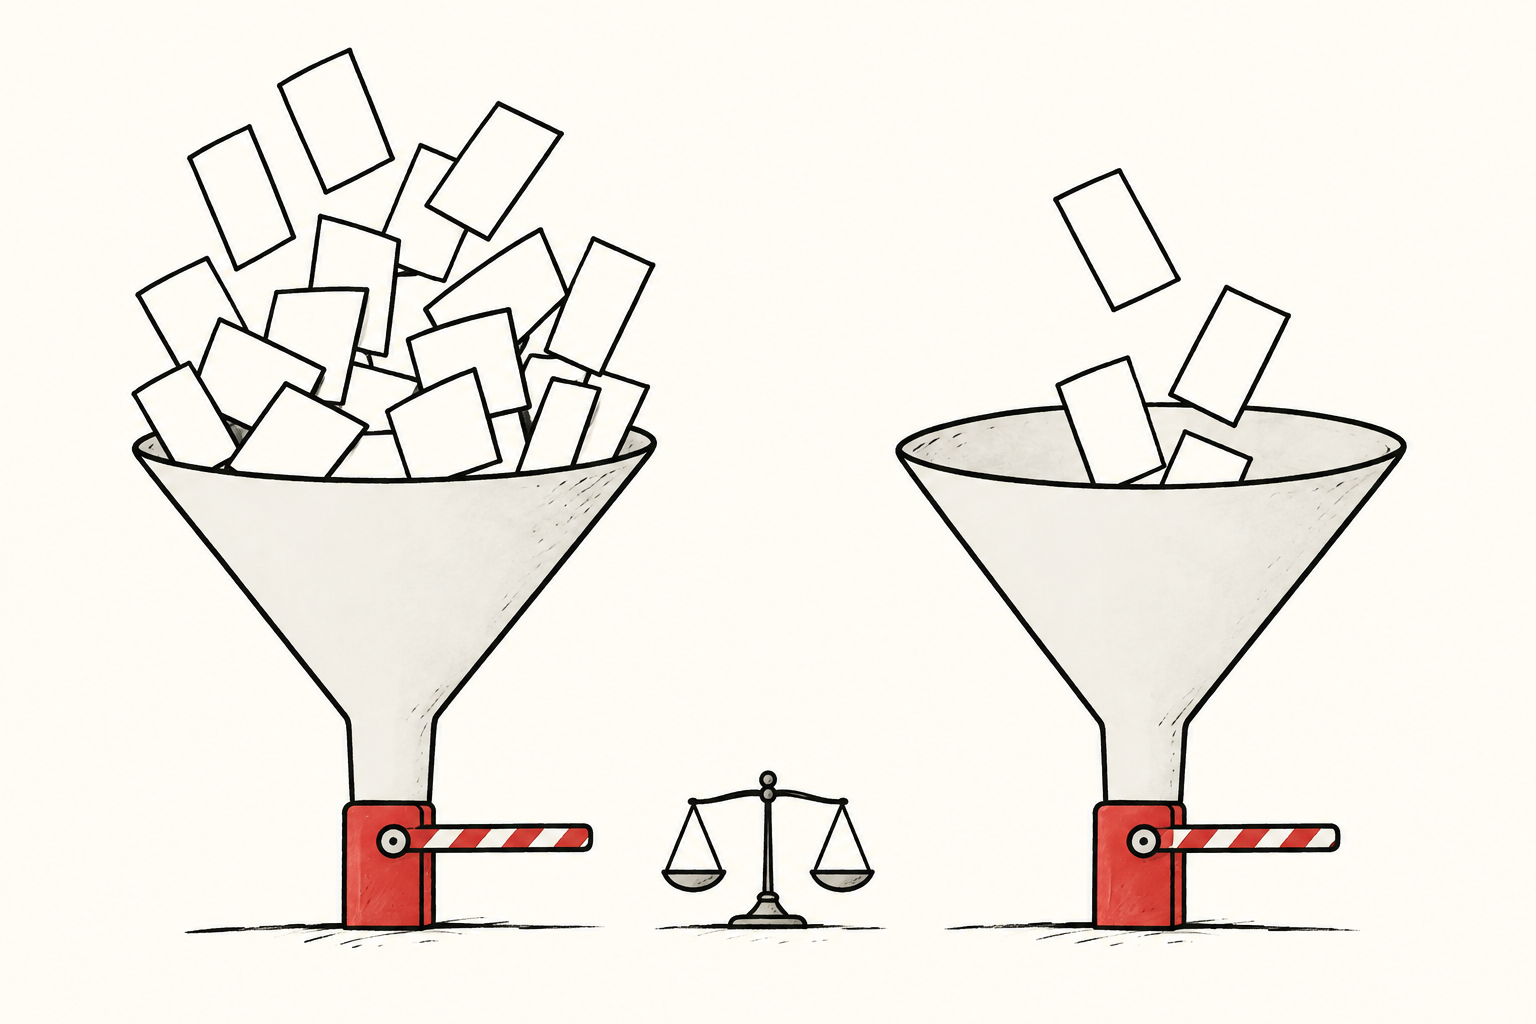
A smaller rights offer can soften per-share dilution while making each new dollar more expensive to raise.
ASGI’s October 16, 2026 update: approximately 3.58 million new shares expected, subject to processing and payments. Results
September prospectus: maximum 10.55 million shares; its illustrative $0.62-per-share dilution assumed full exercise. The fund pays expenses. Prospectus
Analysis: two denominators, two directions
The useful analytical question is how a capital raise changes when fewer investors participate. A smaller issue can cause less dilution of existing net asset value per share while spreading fixed expenses over fewer dollars raised. Those outcomes can coexist. Neither an impressive proceeds headline nor a disappointing participation figure settles the economic assessment.
We propose separating the asset-value calculation from the fundraising-efficiency calculation. The first asks what backs each share immediately after issuance. The second asks how much of the new money survives the costs of obtaining it. Mixing their denominators can make the same transaction look contradictory when it is simply being measured in different ways.
An experiment with invented numbers
Imagine a fictional fund with 100 existing shares and net assets of 2,000 currency units: 20 per share. It offers new shares at 18 and incurs a fixed cost of four units. Assume no portfolio-price changes, distributions, taxes, variable charges or other cash movements. These are invented inputs, not ASGI terms or an estimate of its outcome.
If 30 new shares are issued, gross proceeds are 540. After the fixed cost, net assets become 2,536, spread across 130 shares. NAV per share is approximately 19.51, a reduction of 0.49. The four-unit expense consumes approximately 0.74% of gross proceeds.
If only ten new shares are issued, gross proceeds are 180. Net assets become 2,176 across 110 shares. NAV per share is approximately 19.78, a smaller reduction of 0.22. Yet the identical expense consumes approximately 2.22% of proceeds, three times the earlier proportion.
The smaller issue produces less per-share erosion in this example, but raises money less efficiently. Saying only that dilution improved would miss the cost problem. Saying only that expense intensity worsened would miss the smaller transfer caused by issuing fewer shares below the opening NAV.
The arithmetic also identifies the boundary. The shortfall between the opening NAV and the issue price, multiplied by new shares, plus expenses, equals the dilution amount distributed across all post-issue shares. Change the price, expense structure or portfolio value and the result changes. Partial participation does not mechanically guarantee a better outcome.
Rebuild the comparison after subscriptions
For an actual post-offering review, we would request the finalized share count, cash collected, itemized charges and a consistent opening asset-value baseline. Separate fixed, proportional and tiered charges. A percentage fee cannot automatically be treated like a fixed invoice, and a maximum contractual charge is not evidence of the amount finally paid.
Then calculate two results: the issuance-only change in NAV per share, and total issuance expenses divided by gross proceeds. Reconcile portfolio movements and distributions separately so that a rising market cannot conceal issuance costs. Compare the eventual outcome with a scenario rebuilt using the same date and prices, rather than copying a preliminary illustration into the final record.
The shareholder’s result needs another step
The SEC’s investor bulletin distinguishes a closed-end fund’s market price from its NAV. Investor guide
Our model therefore stops short of a return forecast. A shareholder’s experience also requires the price paid or received, any rights-sale proceeds, additional subscription cash and the value of the remaining holding. NAV dilution alone does not calculate that person’s profit or loss.
The conclusion is conditional but useful: evaluate the cost of the capital actually obtained, alongside its effect on each share. A larger fund and a more efficient financing are separate achievements. This analysis supplies a comparison method, not a recommendation to buy, sell or subscribe.
Information only. No investment, legal, tax, or financial advice.