Anthropic’s IPO has three ledgers: proceeds, control and tradable supply
The headline proceeds, company cash, voting power and shares available to trade are different quantities, even at one IPO price.
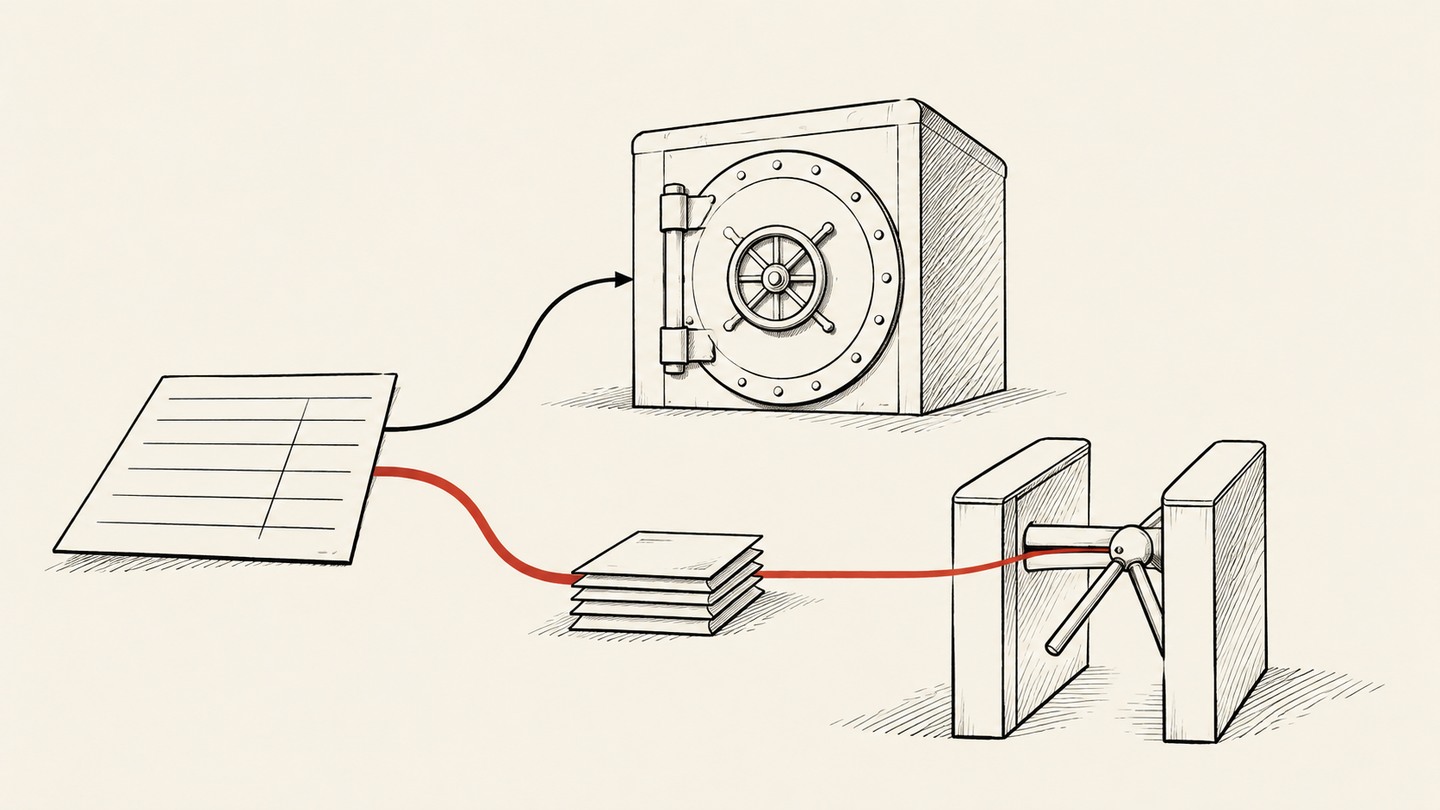
Anthropic’s IPO pricing brings a private AI company’s capital structure under public-market scrutiny. The easiest confusion is not the price per share. It is the difference between three questions: whose account receives the money, who can determine the company’s direction, and which shares can actually enter trading.
The November 18 pricing announcement sets $83 per share for a base offering of 980 million shares. It expects Nasdaq trading under ANT on November 19 and closing on November 20, subject to conditions. This article is written before the first trade. The offer price is not an opening price, and no first-day performance is asserted.
Ledger one: transaction value and company cash
Multiplying the announced shares by the offer price gives $81.34 billion of base public-offering gross proceeds. Anthropic is selling 956,351,354 shares, corresponding to $79.3772 billion. Selling shareholders offer 23,648,646 shares, corresponding to $1.9628 billion. The latter monetizes existing ownership; the company receives none of those proceeds.
The distinction changes how financing capacity should be read. Treating the whole headline as new company cash includes money belonging to sellers. Treating equity financing as revenue confuses a balance-sheet transaction with operating performance. If shares subsequently trade at a higher price, that usually transfers money between market participants; the price difference does not recapitalize the issuer again.
These figures are neither net proceeds nor an already available bank balance. Underwriting discounts, offering expenses and closing need separate treatment. No final Form 424B4 was located in the SEC submissions list checked for this article. We therefore neither use the old filing’s net estimate at an assumed $74 price nor scale it mechanically to $83.
There is also a separate financing channel. The November 17 amended prospectus describes seven strategic investors purchasing an aggregate $26 billion of Class N stock at the IPO price, immediately after completion of the public offering and subject to conditions. This is a concurrent private placement, not public subscription demand or confirmed cash received. A discussion of issuer financing should show its public sale and private placement separately, with conditions and expense conventions stated. Selling-shareholder proceeds do not belong in that total.
Ledger two: economic interest and governance
A sources-of-funds table cannot substitute for a control table. Under the amended filing, Class N generally lacks ordinary voting rights but has economic rights equivalent to Class A, with statutory exceptions and conversion provisions. Large strategic subscriptions can therefore expand economic exposure without automatically delivering the same proportion of general voting power. Conversely, a lack of ordinary votes does not mean a lack of economic dilution.
The single Class F share planned for issuance to the founder entity before closing carries 50.1% of total voting power on matters submitted to shareholders generally, including elections of directors other than Class T directors. Through Class T, the LTBT generally can elect and remove a majority of the board. These are different powers: founder voting on general matters, trust rights over board membership and directors’ responsibility for business decisions need separate reading. The filing also says the trust and trustees do not directly manage day-to-day operations or set strategy. Governance and capital-stock description
Public investors gaining more economic ownership therefore does not necessarily produce a proportional increase in their influence over the board. Nor does a large shareholding by itself establish corporate control. Authority over a specific decision depends on the type of matter, class rights and agreements, rather than a simple addition of share counts.
The structure can support continuity of long-term objectives while making it harder for public shareholders to change direction through ordinary votes. Both implications exist. Offering size or strong subscription interest cannot establish that one has already outweighed the other.
Ledger three: registered shares and trading supply
The November 18 additional registration covers 178,250,000 shares, including 23,250,000 in the incremental underwriters’ option. The remaining 155 million precisely bridges the old 825 million base offering to the final 980 million. Adding that registration again to the final base count would double-count shares.
The final announcement provides a 30-day option for up to 147 million additional shares. At $83, full exercise would represent another $12.201 billion gross. That is a conditional scenario, not financing already completed in the base deal. Registration effectiveness, issuance, settlement and exchange trading are distinct milestones.
Existing ownership is not all immediately saleable either. The preliminary filing sets staged sale arrangements for different holders. Although concurrent-placement Class N is not subject to this offering’s underwriting lock-ups, it remains restricted securities, with resale requiring registration or an exemption. Some transfers can convert Class N into Class A, but the conversion mechanism is not itself permission for immediate sale. Shares eligible for future sale
Fully diluted shares help describe the allocation of economic interests. Offered shares describe this transaction. Actual saleable supply also requires checking class, legal restrictions, release conditions and holders’ willingness to sell. Legal eligibility does not mean every eligible share becomes a sell order that day. We do not transform the old projected supply table into a final first-day float estimate or forecast short-term prices.
What needs checking after pricing
Subsequent documents should complete three evidence chains: actual net proceeds after closing and the private-placement status; effective governance documents and their voting rights; and final share counts, option exercise and staged resale arrangements. They can change independently.
That is what makes the IPO more informative than a very large financing headline. Company funding, shareholder liquidity and public economic ownership can all arise around the same transaction. Their amounts, conditions and decision rights remain different. Keeping the three ledgers separate reveals what going public actually changes.
Information only. No investment, legal, tax, or financial advice.