Reading Intel’s adjusted earnings means checking both directions
An earnings adjustment needs a consistent reason, whether it raises or lowers the reported result.
On October 29, 2026, Intel reported third-quarter diluted EPS of $0.60 under GAAP and $0.52 on its non-GAAP basis. Company release; independent corroboration.
That ordering is a useful starting point for reading a technology company’s earnings. Choosing the larger figure would answer a different question from choosing the measure that best isolates a business mechanism. Neither the word “adjusted” nor the direction of the adjustment settles which information matters. The following is Open Market Notes’ analytical framework, not management guidance or a forecast.
Decide what question the adjustment should answer
A reader interested in product economics may want to understand the relationship between sales and the resources required to deliver them. A shareholder also needs to consider transactions and financing arrangements outside that narrow operating view. Both questions are legitimate. Trouble begins when an answer to the first is silently presented as a complete answer to the second.
An adjustment should therefore have a stated purpose before its effect is known. Imagine a policy that removes a specified class of investment valuation movements to study product operations. Its analytical usefulness depends on applying that policy when the movement hurts reported profit as well as when it helps. Otherwise the resulting series mixes a business definition with a preference for favourable outcomes.
SEC staff guidance warns that excluding unusual charges while retaining unusual gains can be misleading. Non-GAAP interpretations, question 100.03. This is general guidance, not a finding against Intel. Our point is a practical one: read the reason for an exclusion separately from whether its sign is attractive.
A hypothetical bridge makes the issue visible
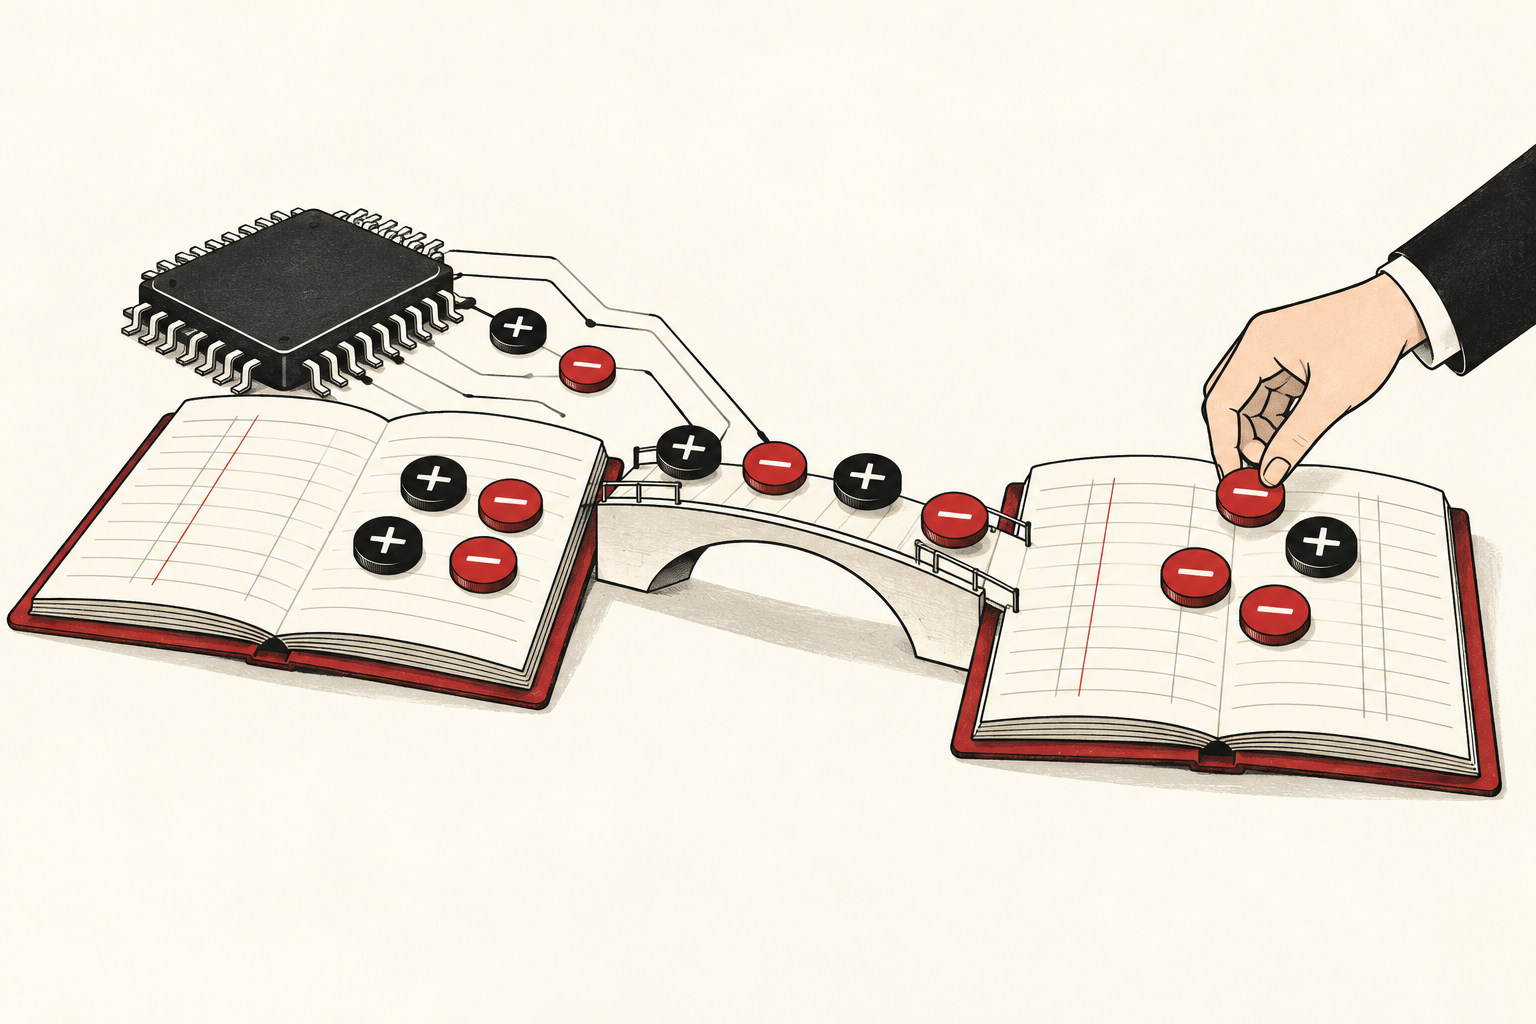
Consider an invented company with reported earnings of 100 units. Suppose those earnings include a valuation gain of 30 and an expense of 10, both excluded under a pre-specified analytical definition. Removing the gain and adding back the expense produces 80. The adjusted number is smaller, although the policy has not become more pessimistic. These are teaching numbers, not Intel estimates.
Now reverse the valuation movement to a loss of 30, holding the underlying business and the expense constant. Reported earnings become 40. Applying the same definition produces 80 again. The useful property is consistency across states of the world, not whether the adjustment gives a company a better headline.
This example does not establish that the excluded expense is economically irrelevant. A cost can be inconvenient for comparison and still consume resources. An analyst can retain one view for comparing operations and a second view for assessing the total cost borne by owners. The two views should remain connected by an intelligible bridge.
A smoother adjusted earnings curve also needs interpretation. It may reflect a steadier business, or simply a definition that removes volatile items. Describing less variation does not, by itself, establish lower economic risk.
Keep the shareholder denominator in view
An earnings comparison can also change when the ownership base changes. For a deliberately simplified illustration, profit of 100 divided among 100 shares gives one unit per share; profit of 110 divided among 125 shares gives 0.88. Business earnings have risen while earnings per share have fallen. No accounting irregularity is needed to produce that result.
Actual EPS calculations are more involved. The IFRS Foundation’s overview discusses earnings numerators and weighted-average share denominators, including dilution. IAS 33 overview. It is a general conceptual reference, not the accounting framework applied to Intel’s US-GAAP filing. For the company itself, the applicable filing and its EPS notes control.
The analytical implication is to keep separate explanations for changes in profit and changes in the claim on that profit. Substituting a period-end share count for the reported weighted average may create a ratio that answers no properly defined question. Conversely, focusing only on dilution can obscure a genuine improvement in the operating business.
The timing at which new shares enter a period’s calculation is different from the total outstanding at its end. Labeling a per-share movement as better or worse operations before checking that basis can assign a capital-structure effect to the product business.
What would make the comparison more useful next quarter?
A usable research record preserves the original reported measure, the adjustment definition and the relevant ownership basis. It should identify any change in definition before comparing growth rates. A new exclusion may be reasonable, but the reader needs to know whether the historical series remains comparable.
Competing interpretations can then be tested. One view may emphasise a cleaner operating comparison; another may argue that repeatedly excluded costs belong in the economic assessment. Evidence about recurrence, cash requirements and the purpose of the expenditure helps distinguish them. Merely preferring GAAP in every case, or non-GAAP in every case, avoids that work.
Intel’s release provides the occasion for this reading exercise, not proof of a complete investment thesis. A per-share profit figure cannot by itself establish production competitiveness, customer durability or future cash generation. Those require their own evidence. The useful conclusion is narrower: choose the question first, preserve the reconciliation, and examine the owner’s share of the result before treating an earnings change as an improvement.
Information only. No investment, legal, tax, or financial advice.