How industrial growth passes through costs and cash flow
A larger invoice can reflect different economics; industrial earnings need a closer look at contribution and cash.
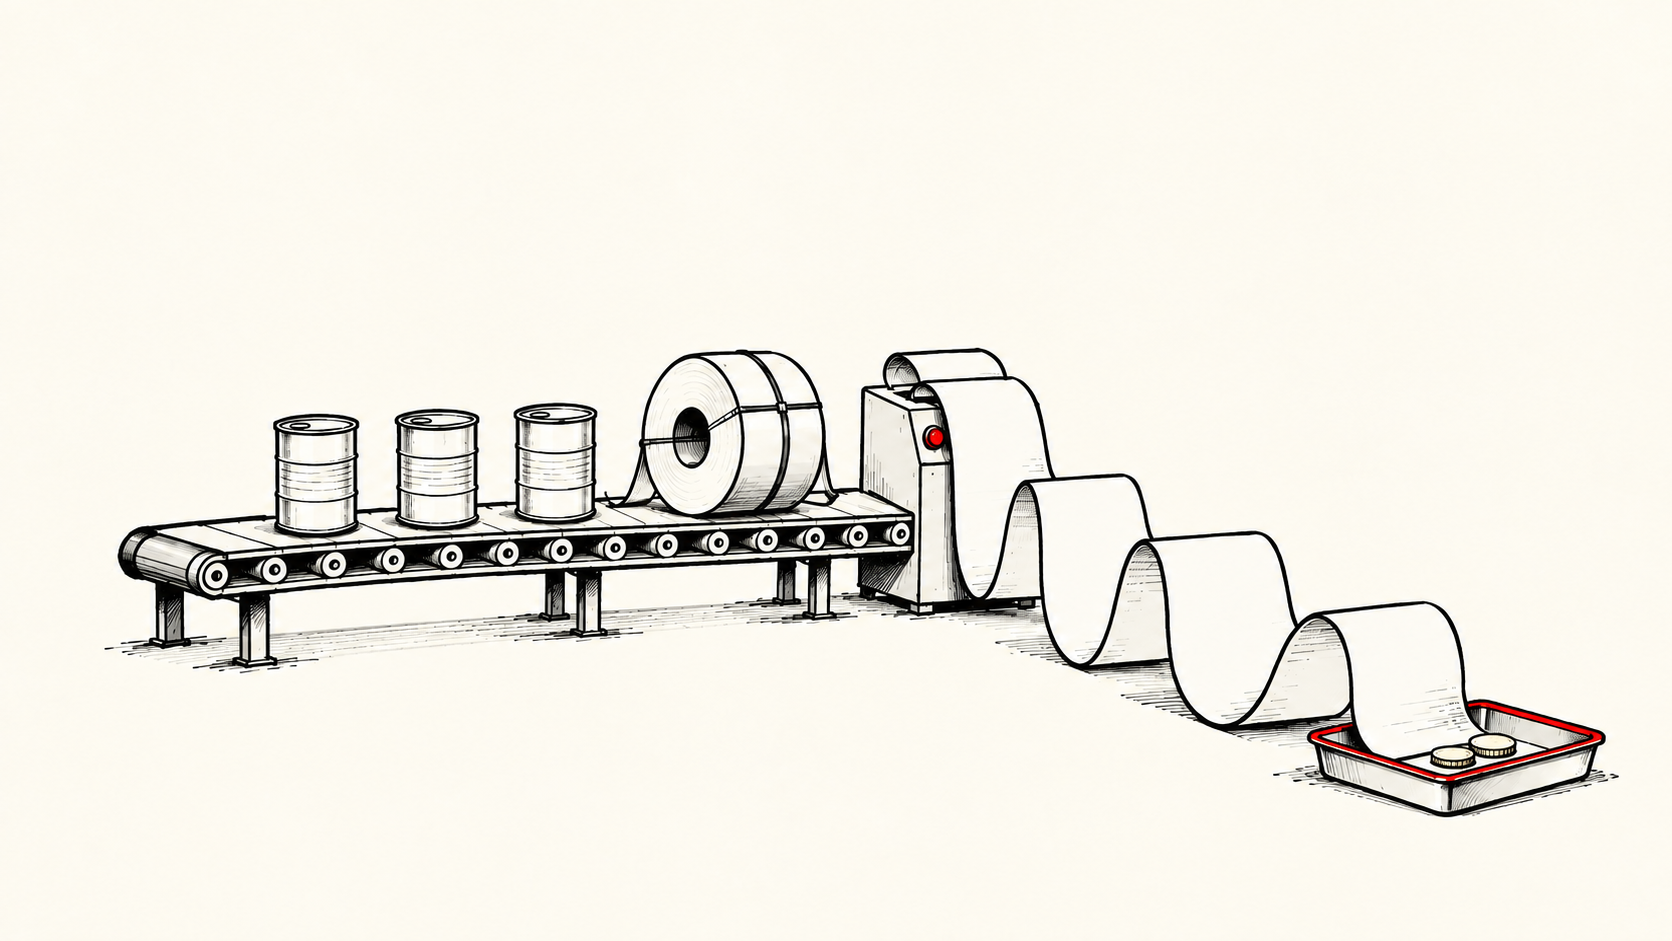
When a company reports revenue growth, a basic question can disappear behind the percentage: if the invoice for the same product has become larger, who actually earns more? For materials-intensive manufacturers, the answer changes how an earnings season should be read.
On October 19, 2026, Crown said its third-quarter sales growth included $405 million of higher material costs passed through to customers. Company results
The same day, Steel Dynamics partly attributed sequential improvement in its steel operations to higher selling prices and lower scrap costs. Company results
These disclosures start a useful discussion; they do not establish which company offers better investment value. What follows is OMN's analytical framework, including hypothetical examples, not an inference about undisclosed contracts, customer behavior or future results.
Take the materials out of the invoice
Imagine a factory charging 100 per unit. Materials cost 60, other production costs 20, leaving gross profit of 20. Materials then rise to 80 and the price increases to 120, with everything else unchanged. Sales rise 20%, gross profit per unit remains 20, and gross margin falls from 20% to about 16.7%. These are illustrative figures, not reported company data.
Revenue growth alone would overstate the additional benefit. The lower margin alone could suggest a deterioration in unit profitability that has not occurred. Both readings omit the same mechanism: additional revenue has simply traveled alongside the cost of materials.
Passing costs through has value. Without it, a manufacturer might absorb the increase. A contractual price-adjustment mechanism can provide protection. But protecting an existing contribution should be distinguished from persuading customers to pay more for the product or service itself. An income statement rarely tells us how much of each is present.
A useful earnings discussion therefore should not equate every increase in price with strong demand. It needs to establish whether quantities rose, the product mix changed, and prices moved under material-indexation clauses. Where those components are unavailable, leaving a question open is more accurate than inserting a macroeconomic narrative.
A better spread is not the final profit figure
Another route to industrial growth is a favorable divergence between selling prices and major input costs. That moves closer to improved unit economics, but other costs still have to be paid.
Consider another hypothetical factory. Its principal material becomes cheaper while customer prices temporarily hold, increasing the amount left on each unit. Yet energy, labor, freight, maintenance and defective output still matter. Frequent overtime to increase production, or poor yields while equipment is commissioned, can offset the benefit of one cheaper input.
Timing also matters. Purchase contracts can reset before or after inventory enters production; finished products can be priced at yet another point. A favorable quarterly spread may reflect better efficiency, or prices that have not yet caught up with one another. Extending one quarter's contribution into every future quarter assumes the very durability that needs to be examined.
The opposite mistake is to dismiss all progress as cyclical luck. Less downtime, better yields and a more useful product mix can have lasting value. Evidence for that interpretation should come from operating disclosures, rather than being inferred backward from rising profit.
Someone has to finance the growth
Profit and cash generation should be read separately, a basic distinction in the SEC's financial-statement guide. SEC explanation
Even a factory that fully passes through material inflation may need more money to sustain the same physical activity. Each tonne in inventory costs more. Customer receivables become larger. Supplier bills may fall due before customers pay.
This need not indicate deterioration. Cash tied up temporarily can return when customers settle, and supplier terms may provide support. Nevertheless, preserving profit does not establish that funding is sufficient. Cash flow improved by delaying payments carries a different implication for the next period than improvement from faster collection or leaner inventories.
The useful evidence is a relationship across periods, not an isolated cash balance. Receivables, inventories and payables belong beside shipment volumes, purchasing prices and seasonality. A working-capital release cannot repeat indefinitely; inventory accumulated for expansion should not automatically be labeled waste either.
Establish a common basis before comparing
Gross profit, segment income, operating profit and adjusted earnings answer different questions. Comparing one manufacturer's segment result with another's consolidated net income can mislead even when the currency and units match.
SEC interpretations call for prominent presentation of the most directly comparable GAAP measure alongside non-GAAP measures, with the necessary reconciliation. SEC interpretations
For readers, the reconciliation explains what has been excluded. It is not simply a choice between believing the reported or adjusted number. New capacity can create costs that temporarily weigh on performance. If expansion continues for years, however, those costs may keep requiring cash. Removing them from a performance measure does not remove the expenditure.
Volume growth also needs its investment context. Extra orders may make better use of existing equipment, or require new lines, warehouses and customer financing. The former can improve utilization of assets already in place; the latter depends on future returns from additional capital. Volume alone cannot distinguish them.
What subsequent disclosures need to answer
The useful question in these industrial results is how growth is being produced, not only whose percentage is highest. Cost-linked pricing calls for attention to unit contribution and funding. Wider spreads raise questions about durability and other expenses. Greater physical deliveries need to be read with capacity, mix and capital requirements.
These mechanisms can coexist and offset one another across businesses. Two companies' announcements describe their disclosed circumstances, not a uniform manufacturing recovery. They also do not establish how share prices should move. Existing expectations, contract execution and the next price reset require further evidence.
A more informative earnings summary explains which additional receipts merely pass through the business, which pay for additional activity, and which may remain available after its costs. That distinction gives a growth rate an economic meaning that can be examined.
Information only. No investment, legal, tax, or financial advice.