Iambic and the Two Ledgers of AI Biotech
Financing and scientific evidence need separate accounts, even when they support the same research programme.
Iambic’s October 16, 2026 filing records charter and bylaw changes connected with completion of its IPO. Its October 14 announcement describes an AI-enabled clinical-stage business and a $150 million gross offering. The final prospectus estimates $135 million net. Combined with existing cash, $75 million is intended for IAM1363 trials, including Phase 2 initiation subject to FDA feedback.
Two accounts, different questions
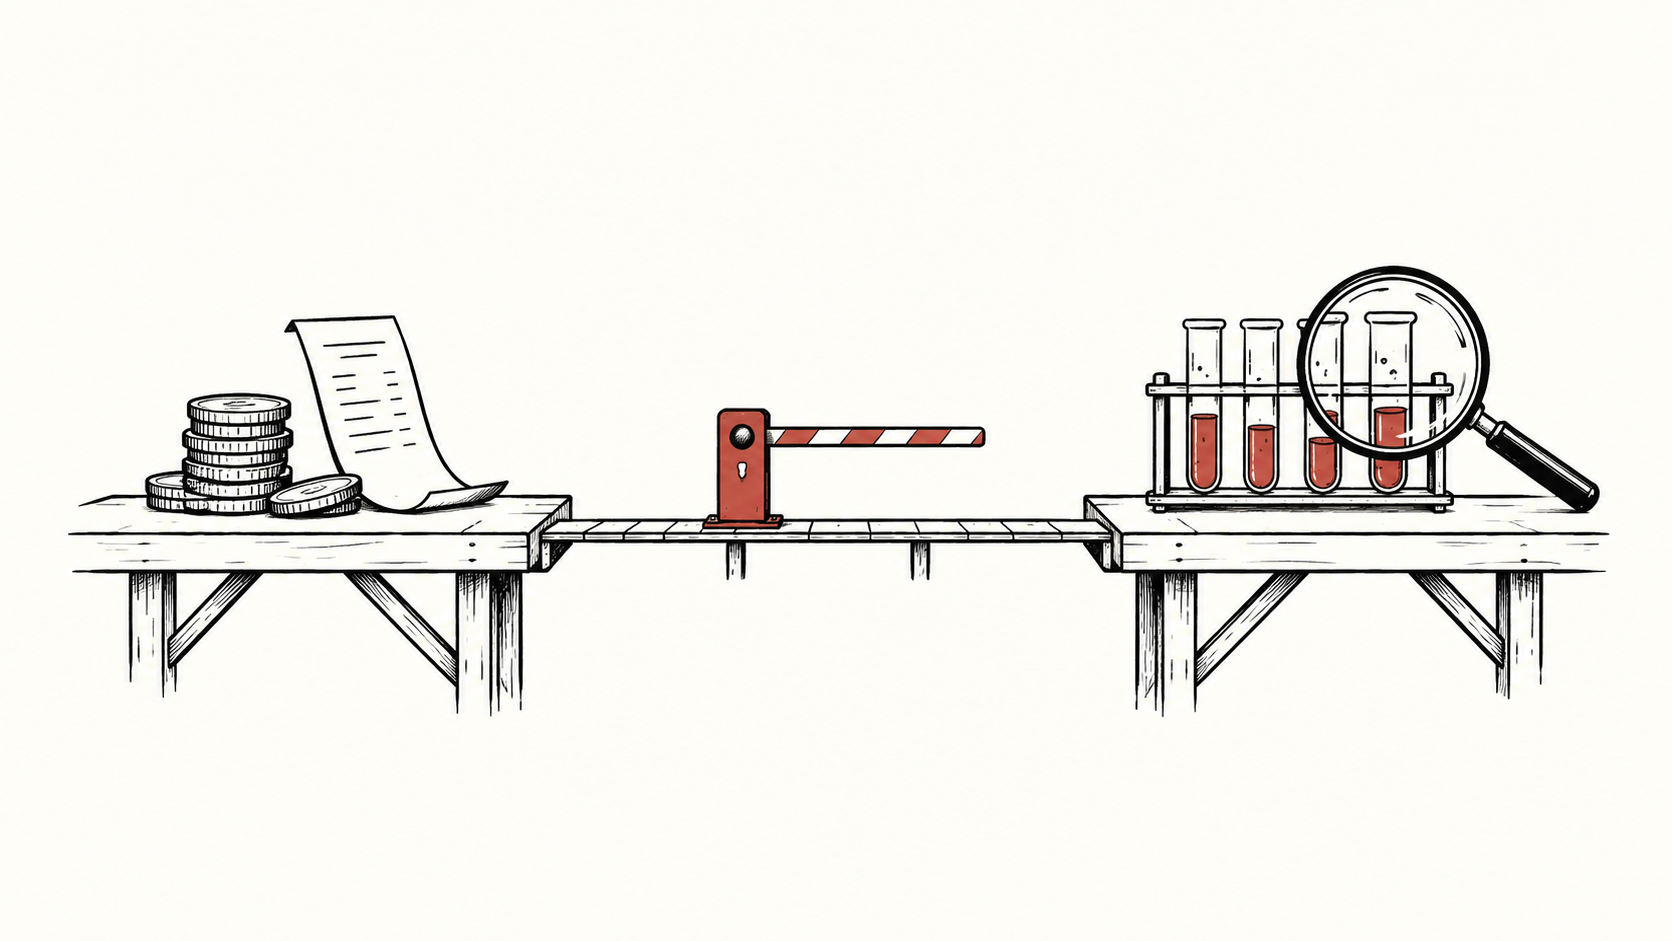
Those documents establish a financing event. Our analytical question is how to describe progress when capital and scientific evidence arrive on different schedules. A useful editorial framework keeps two accounts. The financing account records resources and obligations. The evidence account records what has been tested, what was learned and what remains unresolved. Neither account substitutes for the other.
In a hypothetical research programme, a successful financing could pay for a larger experiment without changing the probability that its central hypothesis is correct. Conversely, an informative negative experiment could weaken a particular candidate while improving the next allocation of research effort. Treating both events as a single score called “progress” hides the distinction that matters.
Record the gate before the result
For each proposed experiment, our framework asks for four entries: the question, the observation that would answer it, the resources committed and the action under each plausible result. These are suggested analytical fields, not a description of Iambic’s internal procedures.
A milestone becomes more informative when its next decision is specified in advance. “More data” is less precise than deciding whether a particular uncertainty has narrowed enough to justify the next test. A larger dataset can still leave the decisive question unanswered. A faster workflow can improve iteration without resolving that question at all.
The same discipline applies to spending. A gross financing headline is not an operating budget. Fees, timing and existing commitments belong in the resource account before any comparison with future research needs. This article does not estimate the company’s cash runway or assign a value to its pipeline.
Leave room for an unfavourable answer
A useful review should make failure legible. It should distinguish an experiment that answers its question negatively from an experiment that cannot answer it because its design or execution is inadequate. The first may produce useful knowledge; the second creates a different task. Neither should be relabelled as success merely because a platform was involved.
The proposed test for future reporting is therefore consistency: can the same programme be followed from resources committed to evidence obtained and then to a changed decision? These offering documents do not answer that question. They provide a timely reason to ask it, without treating market access as scientific validation.
Information only. No investment, legal, tax, or financial advice.