Reading backlog through the conditions of conversion
Backlog becomes more useful when funding, cancellation rights, delivery capacity and collection timing are read together.
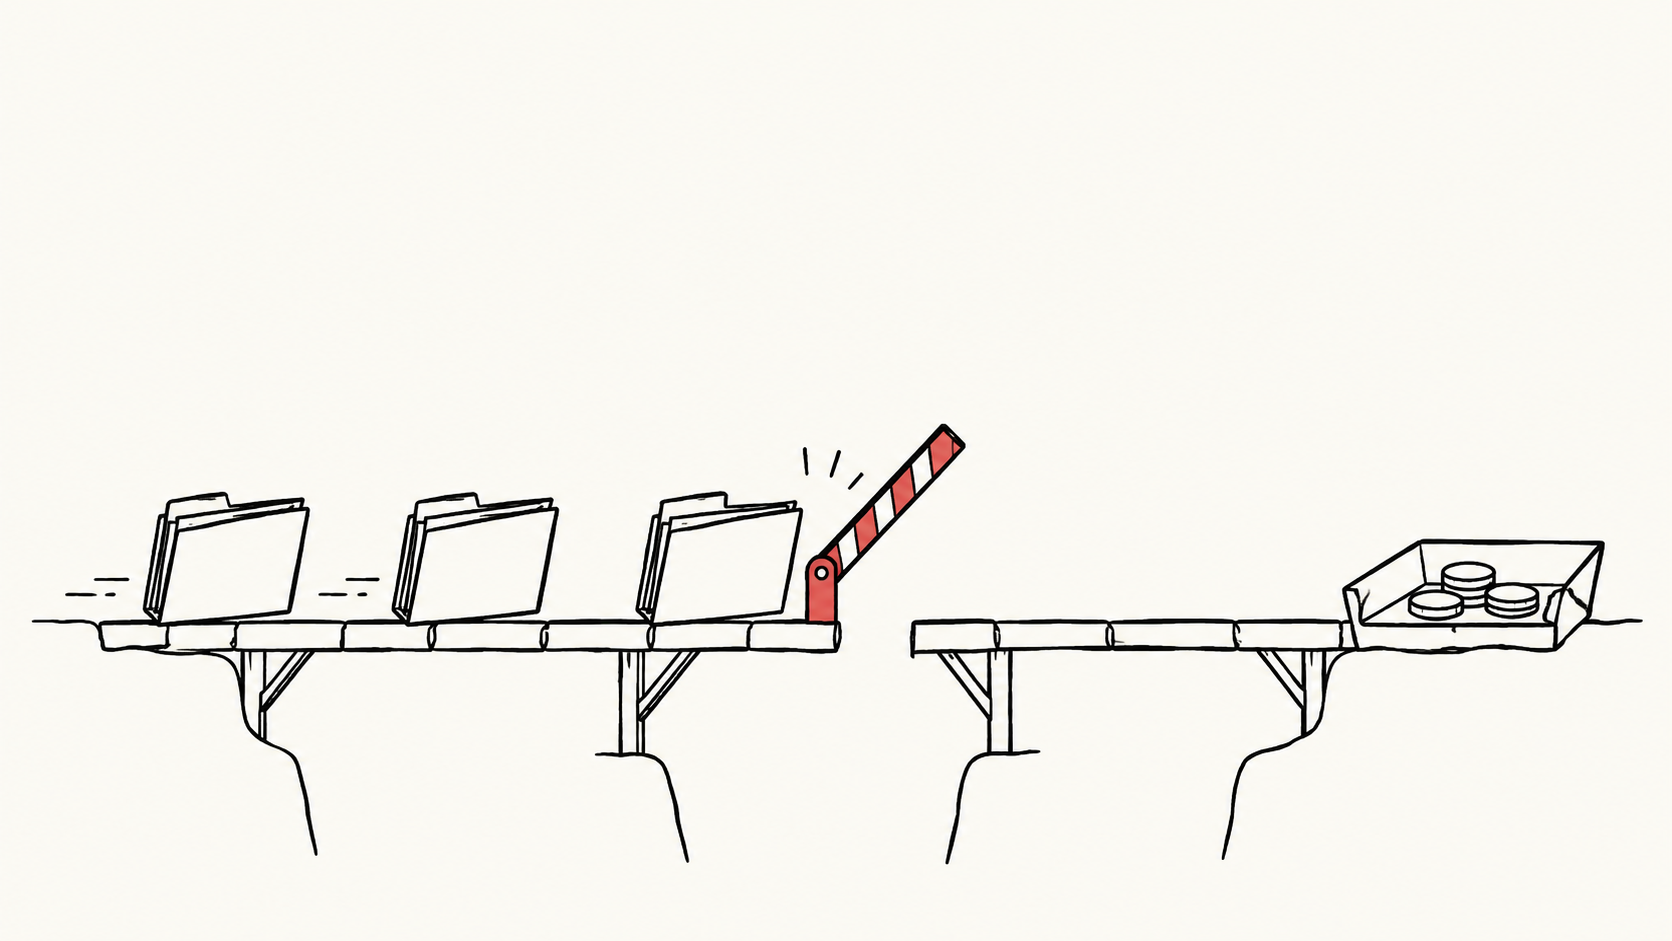
A growing backlog can make a business look easier to forecast just when the work of forecasting becomes more complicated. Contracts have accumulated, but the reported total does not by itself show which customer can withdraw, which project can start, or when the company will be paid. In an earnings season full of forward-looking operating measures, the useful task is to reconstruct those conditions rather than turn a headline balance into a revenue forecast.
This analysis uses earlier public disclosures to explain the distinctions, not to present historical balances as new October results. The argument is straightforward: backlog becomes more informative when it is connected to the decisions and resources required to deliver it. That connection can strengthen a growth story, but it can also show why a large order book is consuming cash.
Start with the right that the number represents
CACI’s fiscal 2026 annual report, filed on August 6, says its unfunded backlog includes work awaiting appropriations and unexercised options. CACI annual report
For an analyst, the implication is not that conditional work is worthless. A customer relationship and an awarded contract may have considerable commercial value before every stage is authorized. The difficulty is that the company and the customer still have decisions to make. A long-duration opportunity should not be assigned the same near-term delivery confidence as work that has a start instruction and an available budget. Conversely, describing all conditional work as speculative would erase useful information about the pipeline.
Consider two hypothetical providers with identical headline order books. One has many short assignments ready to start; the other has a smaller number of multiyear frameworks with optional later phases. A comparison of backlog growth alone would hide the difference. The first may face an immediate staffing burden. The second may have more time to prepare but more exposure to decisions that have not yet been made. Neither profile is inherently superior: the cost of keeping capacity available and the price earned for doing so matter too.
Cancellation protection is not the same as future revenue
Medpace’s 2025 annual report, filed on February 10, 2026, says permitted cancellations or scope reductions typically do not entitle it to all future revenue recorded in backlog. Medpace annual report
That distinction changes the question to ask about a contract. Rather than simply asking whether a customer has signed, ask what economic exposure remains if the work stops. In a hypothetical service agreement, reimbursement of completed work could protect against an unpaid bill while still leaving a newly hired team without its expected next assignment. A cancellation fee might cover some idle time but not the whole profit the provider hoped to earn. Those are different protections, and a headline award value does not reveal which one exists.
It is equally important not to infer cancellation merely from a slow quarter. A delayed start, a redesigned project and a permanently abandoned contract have different consequences. Delay may preserve future work while shifting the costs of waiting onto the supplier. A redesign can create valuable additional work or make the original resource plan inefficient. Without disclosure separating these movements, a precise cancellation estimate would be false precision.
Signing, billing and earning run on different clocks
Salesforce’s February 25, 2026 results release defines remaining performance obligations, or RPO, to include both unearned revenue and unbilled amounts. Salesforce fiscal 2026 results
RPO therefore cannot be treated as a cash account. Nor should a contract-liability balance automatically be read as profit waiting to be released. A liability associated with future service points toward an obligation still to fulfil; judging its economics requires the cost of that fulfilment. Billing, collection and delivery need to be examined separately even when they arise from the same agreement.
A deliberately simplified example makes the timing visible. Suppose a provider sells a twelve-month service for 120 accounting units, collects all 120 at the start and, by assumption, earns the revenue evenly at ten units per month. After three months, it has recognized 30 of revenue and still owes nine months of service. The initial cash receipt did not make the whole contract profitable on day one. The provider must still pay the people and infrastructure needed to serve the customer.
Now suppose the same service is paid monthly in arrears. The delivery schedule and total contract price are unchanged, but the funding requirement is different. If costs are paid before invoices are collected, someone has to finance that interval. These examples are not forecasts or accounting judgments about any named company. They show why two apparently similar contract books can support different working-capital needs, even before margins or defaults are considered.
Follow a group of contracts through time
An end-of-period total mixes older work with new awards. It can rise because demand improves, because contracts become longer, or because execution slows while fresh work continues to arrive. These possibilities are not interchangeable, so the most useful comparison follows a defined group of contracts from one period to the next.
An analytical bridge would start with the opening group, identify work delivered, distinguish cancelled or reduced scope from postponed work, and separately add new business. Currency movements and acquired contracts would sit outside the assessment of internally generated demand. This is a suggested reading method, not a claim that every company provides such a reconciliation or that every reported backlog follows one accounting standard.
The timing distribution matters as much as the total. A shift toward work expected several years away can enlarge the balance without helping next quarter’s utilization. A concentration of near-term starts can instead expose a capacity problem. If a company reports only an aggregate conversion expectation, the honest conclusion may be a range of plausible outcomes rather than a single precise revenue number. Asking for a stable definition and a comparable time horizon is more useful than mechanically dividing backlog by last quarter’s sales.
Capacity determines what the contract is worth
There is a further distinction between having the right to perform work and being able to perform it economically. In a hypothetical engineering business, winning several simultaneous projects could require scarce specialists at higher wages. Subcontracting might protect delivery dates but surrender part of the margin. Starting recruitment too early could increase idle costs; starting too late could delay revenue. A larger book can be commercially encouraging and operationally demanding at the same time.
The opposing case is real as well. Predictable future work can allow better scheduling, reduce repeated selling effort and support investments that would otherwise be hard to justify. The analytical objective is not to discount every commitment. It is to identify which uncertainty has actually been reduced and which cost the supplier has accepted in return.
A useful reading of the next earnings release would therefore connect the reported balance to enforceable scope, authorization, delivery timing and cash collection, while keeping the company’s own definitions intact. Where the evidence stops, the forecast should become less precise. Backlog is most valuable as a way to understand the route to future business, including the obligations along that route, rather than as a substitute for the business already completed.
Information only. No investment, legal, tax, or financial advice.