After ASEAN’s digital pact, what changes on a merchant’s next order?
The value of digital trade rules will depend on reusable records, connected services and measurable order-processing costs.
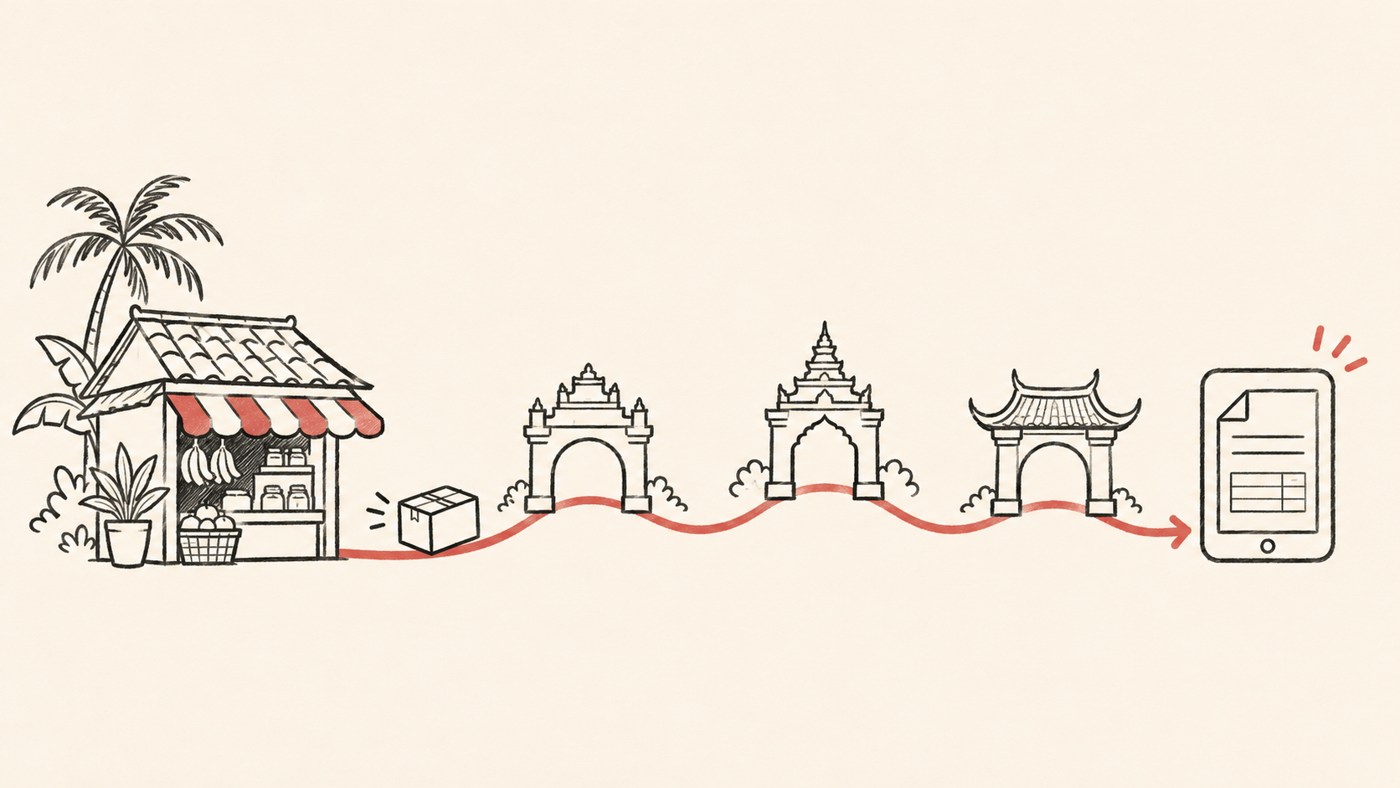
ASEAN signed its Digital Economy Framework Agreement, or DEFA, in Manila on November 14, 2026. ASEAN announcement This is an important institutional step for cross-border merchants, not evidence that every regional market can already be served through an identical process.
The useful business question is what a merchant no longer has to repeat when entering a second market or fulfilling the next order. Integration becomes commercially meaningful through those details. Market-size forecasts alone can obscure the costs of onboarding, reconciliation and customer support.
A signature is not an operating service
Singapore’s official factsheet describes digital trade, cross-border data and payments among the agreement’s areas. It says entry into force follows signing by 180 days, with the text due in early 2027. Official factsheet, Annex A ASEAN’s secretary-general also identified ratification and implementation planning as subsequent work. Signing-day remarks
These sources establish a signed framework and a next stage of implementation. They do not establish that a merchant’s specific national documentation, licensing or customs requirements have already disappeared. Operational changes should be checked against the published scope, implementing material and available services.
Businesses need a more practical calendar than a signing date: when their workflow changes, which provider supports it, and whether existing and new customers face different onboarding routes. Institutional certainty must become something a company can use to plan staffing and budgets.
Follow one order through the business
Consider a hypothetical small homewares merchant already selling domestically and preparing to enter a neighboring country. This example is an analytical illustration, not a service guaranteed by DEFA.
The marketplace, payment provider and logistics operator first need to identify the same business. Product, invoice, payment and parcel records then need to refer to the same order. Different formats can require repeated entry, document conversion and explanations. Each step may look inexpensive in isolation, yet the accumulated staff time can determine whether a small order is worthwhile.
Interoperability may first create value by reducing repetition, rather than making cross-border trade costless. If an accepted electronic record can be reused across the workflow, staff may spend less time checking identical information in several systems. This is a mechanism to test, not a measured outcome of the agreement.
A merchant could record which information is supplied once, which is supplied repeatedly and which exceptions require manual intervention in each market. Comparing those records before and after implementation is more informative than counting new software connections.
Data movement needs shared meaning
Regional digital trade did not begin this week. ASEAN’s earlier e-commerce agreement entered into force in December 2021. ASEAN background The new framework should therefore be assessed by what it adds to existing operations, not by treating all online regional trade as a new activity.
From a service-design perspective, moving data is only one requirement. Systems must distinguish the recipient, buyer, payer and merchant, and know when information changed, how errors are withdrawn and who resolves a mismatch.
An address updated in the order system but not in logistics or customer support can create a real loss. Adding interfaces alone will not solve that. A dependable design preserves revision times, status and responsibility so different providers can identify the correct record. These are operating principles, not an interpretation that adds obligations to the treaty.
Payment is not the end of an order
A successful payment completes one part of a commercial process. The merchant still needs to match funds to the order, identify who initiates a refund, record returns and partial refunds, and know whom to contact about reconciliation differences.
Payment interoperability should consequently be evaluated beyond the appearance of a checkout screen. Can the merchant identify an order through payment, cancellation, refund and dispute? The normal path is easy to demonstrate; exceptions often reveal whether services are genuinely connected.
This matters when choosing providers. An apparently inexpensive payment entry point may be unsuitable for a small team if it creates substantial manual checking. This article does not compare provider prices. The analytical point is to put explicit fees and internal handling costs in the same operating record.
Easier access can also concentrate dependence
More coordinated regional rules could help providers standardize cross-market onboarding. A merchant without a technical team could use an integrated service rather than maintain every interface independently.
Convenience does not necessarily increase choice. If order history, refunds and customer access all depend on one platform, switching can remain costly. This is general platform-economics analysis, not an allegation about a company or the agreement.
Merchants should examine whether procedures are reusable and whether records can be exported in a clear, reconcilable form. Integration’s benefits depend both on rules and on how products turn them into usable capabilities.
Our assessment is that DEFA’s commercial value should be tested through subsequent order evidence: less repeated submission, shorter exception handling and more predictable expansion costs. Signing establishes a shared direction. The improvement a merchant experiences must appear in actual transactions.
Information only. No investment, legal, tax, or financial advice.